
By Admin | 17 October 2026
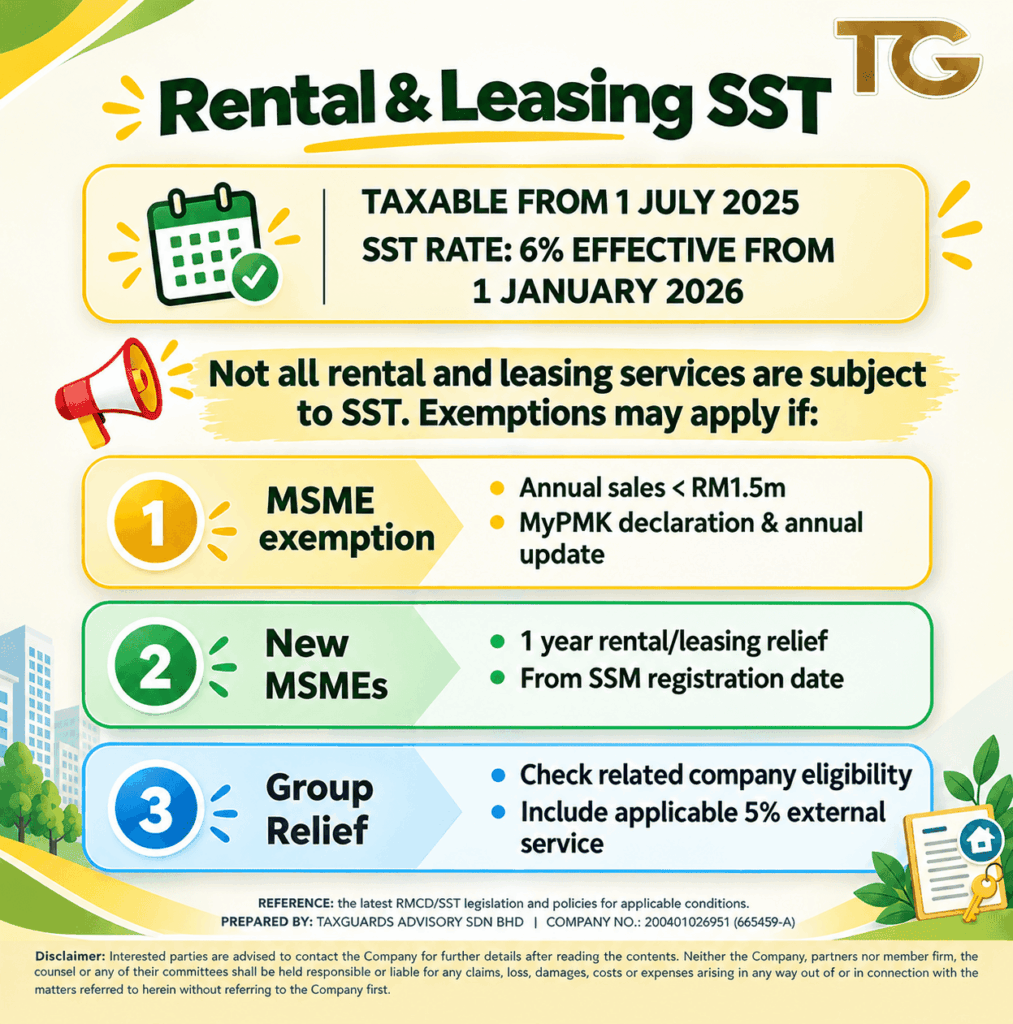
Rental and leasing services under Group K became subject to SST from 1 July 2025, with the SST rate revised to 6% from 1 January 2026.
Before charging SST, businesses should consider the applicable exemptions and reliefs, including:
🔹MSME exemption – Businesses with annual sales of RM1.5 million or below may qualify, subject to the relevant MyPMK requirements.
🔹New MSMEs – Eligible new MSMEs may qualify for 1-year rental/leasing SST relief from their SSM registration date.
🔹Group Relief – Related companies should assess whether they qualify for group relief, including the applicable 5% external-service condition.
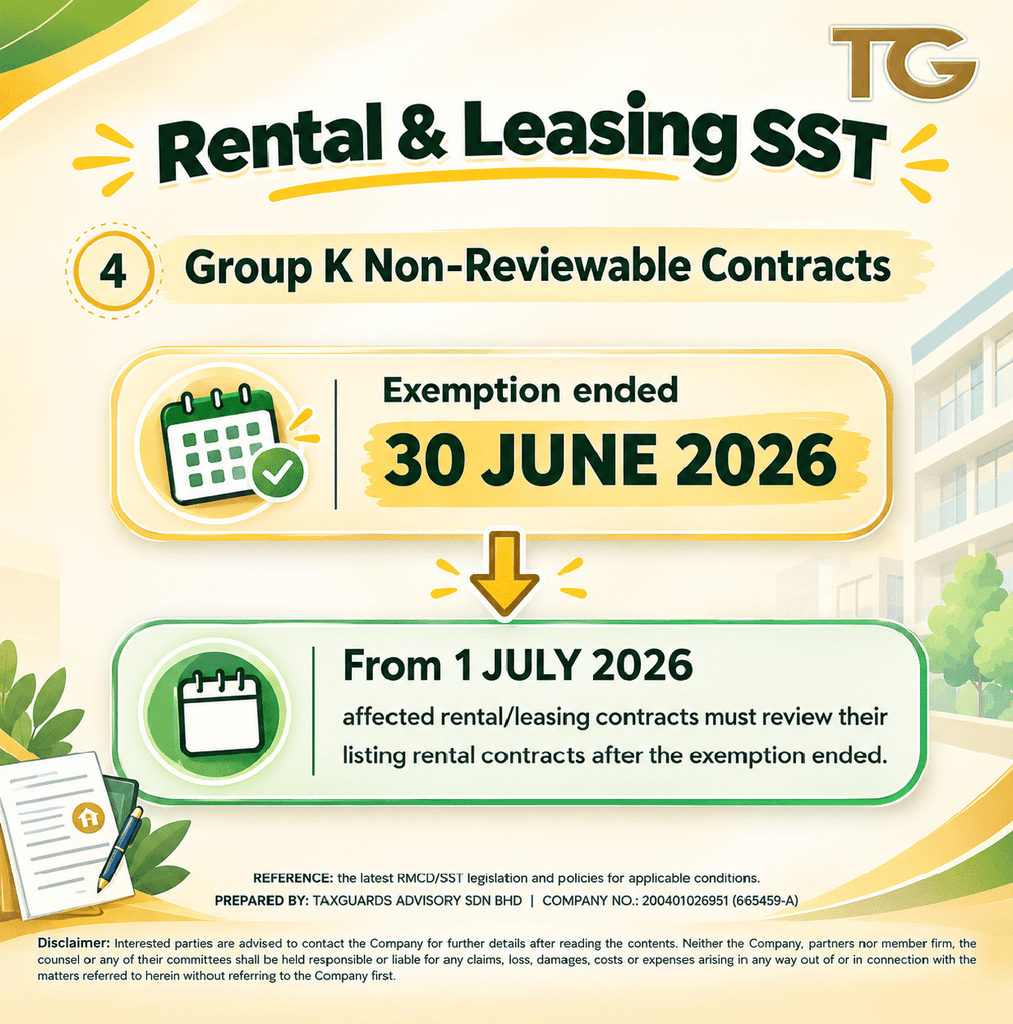
🔹Non-reviewable contracts – With the exemption ending on 30 June 2026, affected contracts should be reviewed from 1 July 2026.
📌 Businesses are encouraged to review their SST obligations and refer to the latest RMCD/SST legislation, guidelines and policies for the applicable conditions.
📩 For further assistance, contact us at:
info@taxguardsadvisory.com