
By Admin | 24 October 2026
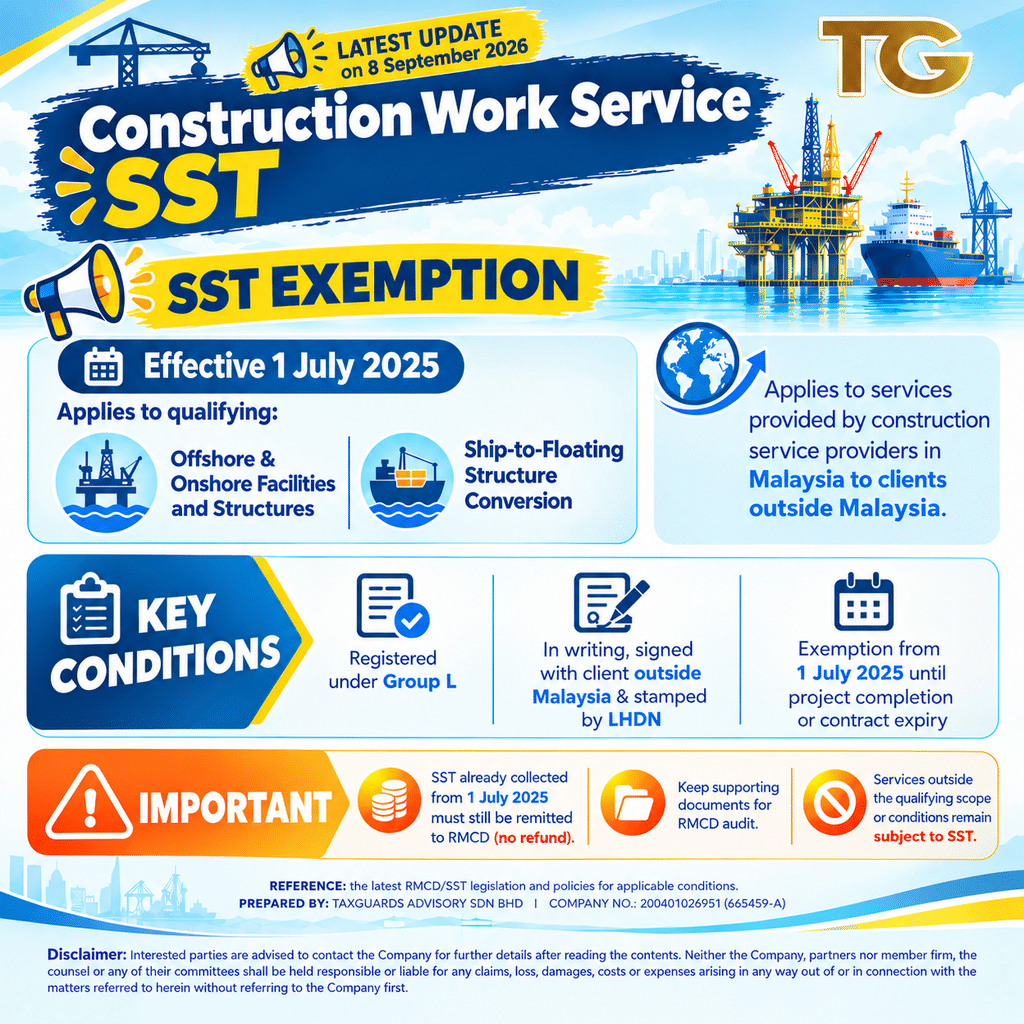
🏗️ CONSTRUCTION WORK SERVICE SST EXEMPTION
📢 LATEST UPDATE – 8 SEPTEMBER 2026
Effective 1 July 2025, service tax exemption applies to qualifying:
🌊 Construction of Offshore & Onshore Facilities and Structures
🚢 Ship-to-Floating Structure Conversion
📌 The exemption applies where services are provided by construction service providers in Malaysia to clients outside Malaysia, subject to the prescribed conditions.
KEY CONDITIONS
- Provider must be registered under Group L.
- The contract must be in writing, signed with the client outside Malaysia, and duly stamped by LHDN.
- The exemption applies from 1 July 2025 until project completion or contract expiry.
- Every invoice must include the prescribed SST exemption statement:
“Service tax exemption under paragraph 34(3)(a) and subsection 34(4) of the Service Tax Act 2018 pursuant to STP No. 5/2026 dated 8 September 2026.”
⚠️ IMPORTANT REMINDERS
- SST collected from 1 July 2025 must still be remitted to RMCD. No refund is available.
- Relevant supporting documents must be retained for RMCD audit purposes.
- Services outside the qualifying scope or conditions remain subject to SST.
📩 Need assistance?
Contact us at info@taxguardsadvisory.com