
By Admin | 12 September 2026
Your company may qualify for Malaysia’s preferential SME tax rates if it meets the relevant conditions, including:
✅ Malaysian tax resident and incorporated in Malaysia
✅ Paid-up ordinary share capital ≤ RM2.5 million
✅ Gross business income ≤ RM50 million
✅ Meets the relevant related-company ownership requirements
✅ Foreign ownership does not exceed 20%
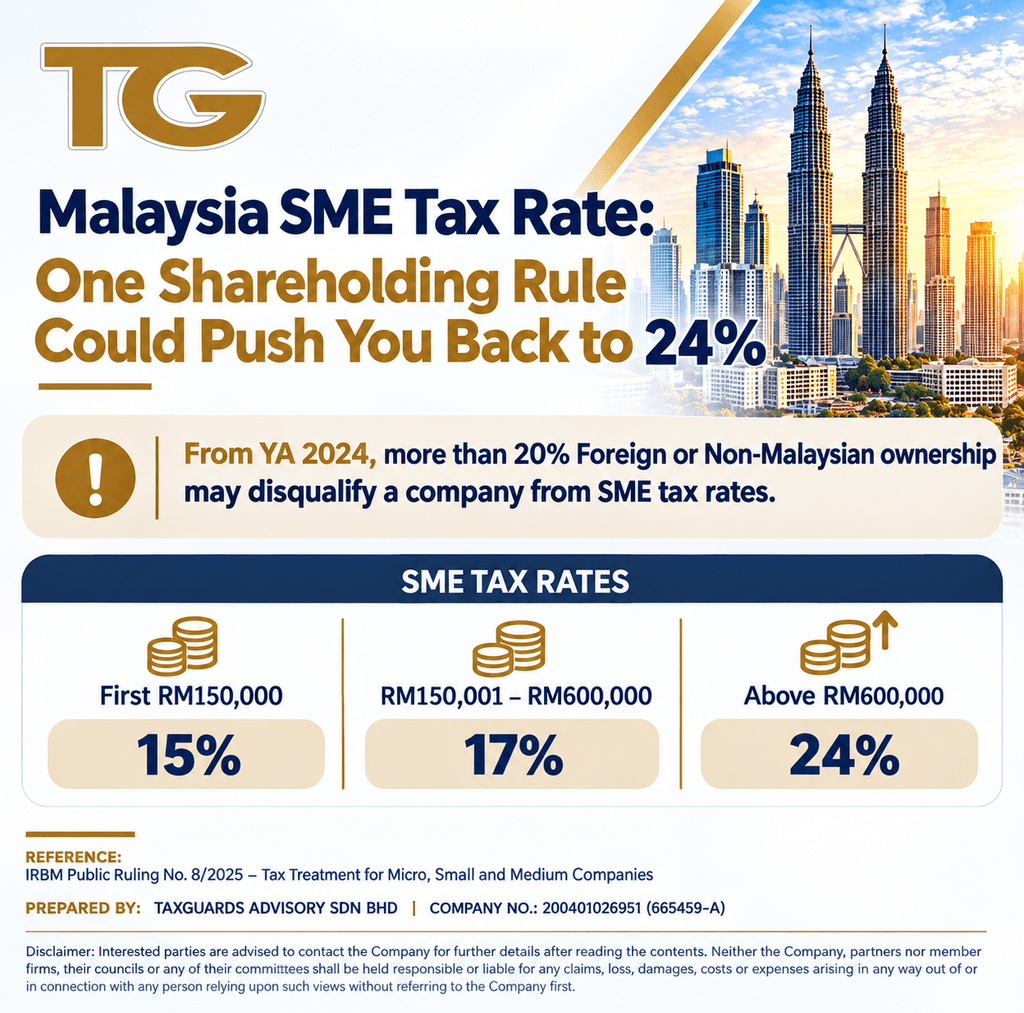
From YA 2024, more than 20% foreign ownership by a foreign-incorporated company or non-Malaysian citizen may result in the company losing its preferential SME tax rate.
For qualifying companies:
💰 First RM150,000 — 15%
💰 RM150,001 to RM600,000 — 17%
💰 Above RM600,000 — 24%
📌 Shareholding structure matters — not just capital and turnover.
Based on IRBM Public Ruling No. 8/2025 – Tax Treatment for Micro, Small and Medium Companies.
📩 For further assistance, contact us at
info@taxguardsadvisory.com